
A complete two-checkpoint example
These synthetic USD figures use the same household scope and valuation method on both dates. Assets rise by $20,000 and debt falls by $5,000, so net worth rises by $25,000. The difference describes balances, not an investment return. July and August were not recorded; there are no invented values for those months.
| Recorded date | Assets | Liabilities | Net worth |
|---|---|---|---|
| 30 June 2026 | $500,000 | $180,000 | $320,000 |
| 30 September 2026 | $520,000 | $175,000 | $345,000 |
| Change between recorded dates | +$20,000 | −$5,000 | +$25,000 |
Follow the cash when debt is repaid
Paying principal with cash you already own reduces assets and liabilities by the same amount. It does not create net worth at that moment. In this synthetic USD example, a $5,000 payment contains principal only; there is no interest, fee, tax, or market movement.
| Position | Cash | Other assets | Debt | Net worth |
|---|---|---|---|---|
| Before repayment | $20,000 | $480,000 | $180,000 | $320,000 |
| After $5,000 principal payment | $15,000 | $480,000 | $175,000 | $320,000 |
| Immediate change | −$5,000 | $0 | −$5,000 | $0 |
Reconcile the change without counting repayment twice
One possible explanation of the two-checkpoint example is shown below. It is an invented reconciliation, not something the two totals prove. Retained income means income left after spending and costs, before this principal payment. A contribution from another included account would be a transfer instead of new wealth.
| Event | Asset change | Debt change | Net worth change |
|---|---|---|---|
| Retained income added to cash | +$12,000 | $0 | +$12,000 |
| Market value increase | +$10,000 | $0 | +$10,000 |
| Property estimate correction | +$3,000 | $0 | +$3,000 |
| Cash pays loan principal | −$5,000 | −$5,000 | $0 |
| Total movement | +$20,000 | −$5,000 | +$25,000 |
See a recorded position in the product
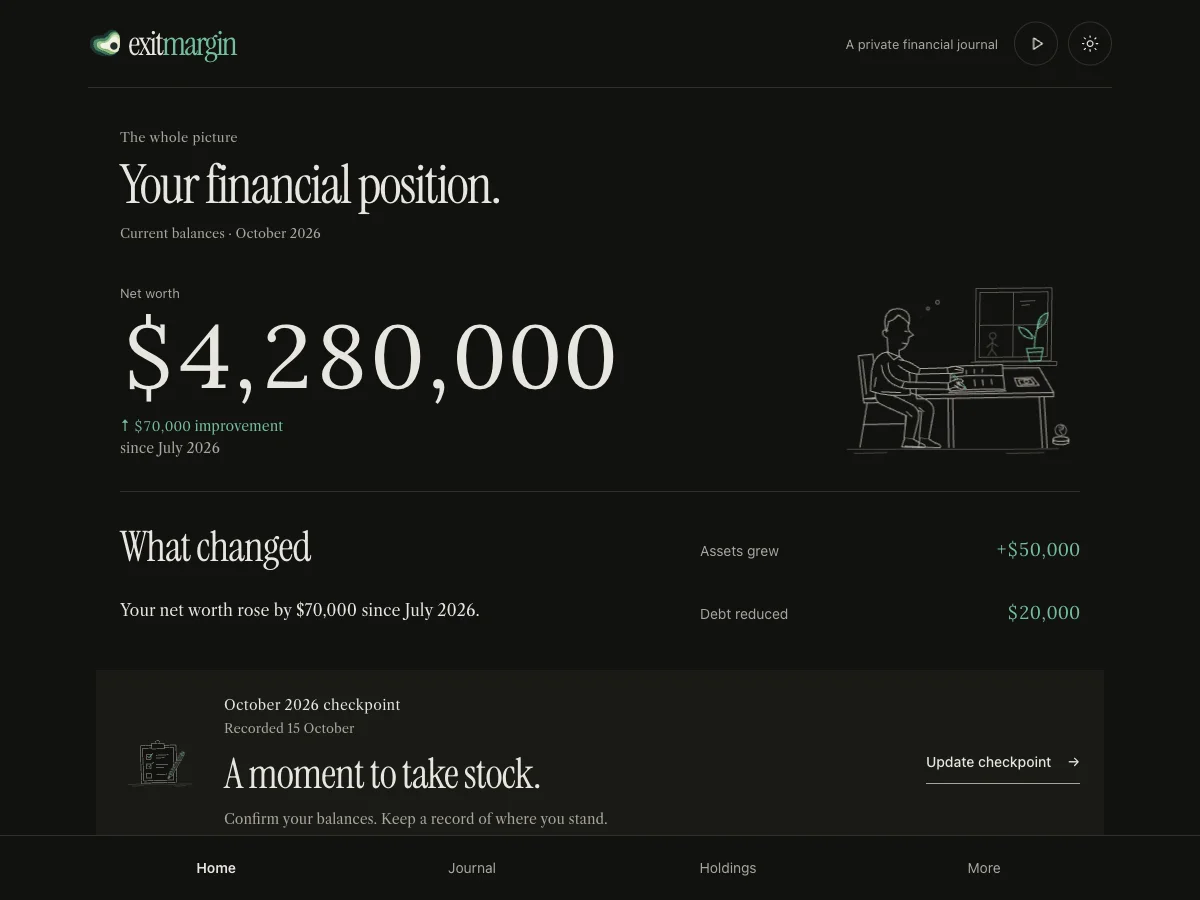
The screenshot below comes from Exitmargin’s interactive example journal. It uses a separate synthetic dataset, not the two-checkpoint figures above. No real financial records are shown. Open the example to inspect its navigation and recorded months.
Why a net worth history is useful
Income tells you what comes in. A portfolio shows part of what you own. Net worth brings your assets and debts together. A series of dated positions can show whether savings are building, debt is changing, or more of your wealth sits in property than you expected.
It is an incomplete measure. Net worth does not show next month’s bills, the safety of an investment, or whether money is available to spend. A higher total is not a measure of personal success. Keep a separate cash-flow plan if that is the question you need to answer.
1. Choose the scope before collecting balances
Decide whether this is an individual or household record. Include only your ownership share in an individual record. Choose one reporting currency and a valuation date. Write down those choices so future snapshots describe the same financial life.
List accounts and holdings, not transactions. Cash, deposits, investments, retirement accounts, property, and reasonably valued personal or business assets can belong in the record. List mortgages, other loans, and credit card debt separately.
2. Calculate an honest baseline
Use current statement balances for cash and debts. Use current investment values rather than the amounts originally invested. Use reasonable estimates for property and other assets without a quoted price. Record the date and basis of each estimate in your worksheet or notes.
Add assets and subtract liabilities. For example, assets of 500,000 and debts of 180,000 give net worth of 320,000 in one currency. Keep a negative result if debts exceed assets. Do not add an unexplained balancing entry to reach an expected total.
3. Save dated snapshots instead of replacing history
Keep the date, asset total, debt total, and net worth, plus the underlying balances if your tool supports them. Save the original position before entering a later one. A total without its components is harder to explain or correct.
A spreadsheet can use one dated tab per checkpoint and a small summary table. A dedicated tracker can preserve the recorded balances for you. In Exitmargin, checkpoints retain the balances and holding names recorded for a month. Missing months stay empty; the app does not invent balances between them.
4. Choose monthly or quarterly reviews
Monthly recording can work well when statements are easy to collect or debt is changing regularly. Quarterly recording may be enough when you want a longer view with less administration. Use a date you can repeat, such as the last available statement date near month-end.
This is a practical choice, not a financial rule. Daily market movements rarely require a new personal balance sheet. Check accounts more often when needed for bills or fraud detection; those tasks do not require frequent net worth snapshots.
5. Review what changed
Suppose the next snapshot has assets of 520,000 and debt of 175,000. Net worth is 345,000, up 25,000. That consists of 20,000 more assets and 5,000 less debt. Compare the asset and debt totals separately before looking only at the final number.
The arithmetic does not prove the cause. The extra assets might include saving, market movement, a gift, or a corrected valuation. Moving 10,000 from cash to an investment does not itself create 10,000 of new wealth. Keep a short note outside the app when context matters; the current journal stores balance checkpoints, not separate decision notes.
Keep market movements and estimates in context
A lower snapshot during a market decline is still a useful record. Do not change the valuation method only to smooth a disappointing result. Use the same date convention and record a material correction rather than quietly replacing the meaning of the series.
Property and business estimates may be less precise than account balances. You can keep an estimate between reviews if it remains reasonable, but label its age in your working notes. An unchanged estimate is not proof that the asset’s value was unchanged.
A checklist for your next checkpoint
Use this checklist on screen or print this guide. Keep valuation notes in your worksheet or existing notes; the current journal does not store separate decision notes.
- Choose the date, ownership scope, and reporting currency.
- Check current assets and outstanding debts against statements.
- Check transfers, account closures, ownership shares, and duplicate entries.
- Separate retained income, market changes, and estimate corrections where records support it.
- Save the checked balances with the real date. Leave missed months empty.
- Preserve a private backup and finish the review.
Choose tools with clear limits
A spreadsheet offers flexible formulas, valuation notes, and custom columns. A journal makes recurring snapshots easier to revisit. Use whichever helps you preserve a consistent record without duplicate entries. Export backups before moving between devices or replacing a file.
For private manual tracking, open providers separately and enter balances without sharing bank credentials. Check where the chosen tool stores records, whether it encrypts them, and how recovery works. Exitmargin keeps financial records in the browser without bank linking; its database and backup files are not encrypted. You still need a private backup.
Finish when the position is accurate enough for its purpose. You do not need to keep checking until the number changes. The point is to understand your financial life over time.
Sources and scope
These are general explanations and product instructions, not personal investment, tax, or debt advice. The examples are synthetic. Product instructions describe the current app.
For product details, read How it works and Data & privacy. Report a correction through Help & contact.